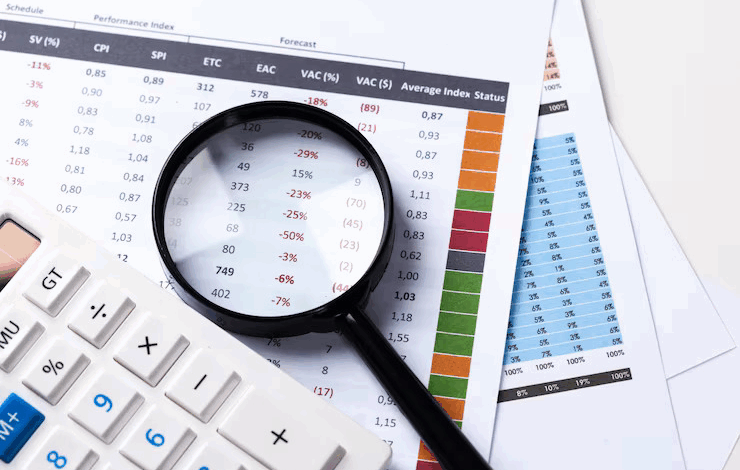
Running a business successfully requires more than just great ideas and customer service. Every entrepreneur must track financial performance to ensure long-term stability. One of the most essential documents for this purpose is the profit and loss statement for small business. This financial report provides a clear summary of revenues, expenses, and net income over a specific period. Without it, small businesses risk losing control over cash flow and profitability. If you’re looking for reliable tools and resources to improve your financial reporting, check out https://dzar.org/.
A profit and loss statement (P&L) is sometimes referred to as an income statement. It shows whether your business is making money or running at a loss. For small businesses, this report is critical because it gives insight into how effectively resources are being used. Unlike balance sheets, which provide a snapshot of assets and liabilities, a P&L focuses on the company’s operational performance. This means owners can quickly identify weak spots, such as rising expenses or declining sales, and take action before problems escalate.
Another reason why the profit and loss statement for small business matters is that it helps with external communication. Investors, banks, and potential partners often require this document when assessing a company’s financial health. If you’re applying for a loan, lenders will want to see whether your revenue consistently exceeds expenses. By having a detailed and accurate P&L, you increase your chances of securing funding and growing your operations.
Profit and Loss Statement for Self-Employed
Freelancers, contractors, and gig workers often underestimate the importance of structured accounting. However, a profit and loss statement for self-employed professionals is just as valuable as it is for larger businesses. This document helps track project-based income, operational costs, and net profits, ensuring that you’re not underreporting or overpaying taxes.
For example, if you are a self-employed graphic designer, your P&L would list earnings from different clients, followed by expenses such as software subscriptions, internet bills, and marketing costs. By keeping these details organized, you’ll know exactly how much money you are truly making after expenses. Moreover, a profit and loss statement for self-employed individuals provides an excellent record for tax season. When filing taxes, you need to justify income and deductions. With a P&L, everything is structured and verifiable.
Additionally, self-employed people often face fluctuating incomes. Some months may be more profitable than others. By reviewing your P&L regularly, you can forecast future earnings, set aside money for taxes, and plan for slower periods. This financial discipline ensures stability and reduces stress, especially in industries where income is seasonal or client-based.
See also: Transforming Marketing Strategies with Enterprise Ad Tech Solutions
Personal Profit and Loss Statement
While businesses use P&L statements regularly, individuals can also benefit from them. A personal profit and loss statement helps people understand their income, expenses, and savings in a structured way. Essentially, it’s a household version of the business P&L.
For instance, your personal P&L might include your salary, rental income, or side hustle earnings as revenue. On the expense side, you’d list mortgage or rent payments, utilities, groceries, insurance, and leisure activities. The difference between income and expenses shows your net savings (or losses).
Creating a personal profit and loss statement helps individuals achieve financial clarity. It’s especially useful for people working toward big goals such as buying a home, paying off debt, or saving for retirement. When you can see where your money goes, it becomes easier to adjust habits, cut unnecessary spending, and prioritize long-term goals.
Moreover, lenders sometimes request a personal P&L when evaluating loan applications, especially for mortgages or personal business loans. Presenting a structured statement demonstrates responsibility and financial awareness, giving you an advantage when negotiating terms.
Profit and Loss Statement for Service Business
Service-based companies, such as consultants, agencies, or repair shops, need detailed financial tracking just as much as product-based businesses. A profit and loss statement for service business allows owners to see exactly how revenue streams and operational expenses affect net income. Unlike product companies that track inventory costs, service businesses primarily monitor labor, software, marketing, and other overhead costs.
By analyzing the profit and loss statement for service business, managers can determine which services are most profitable and which may need adjustments. For example, if a marketing agency notices that certain packages have higher operational costs than revenue generated, they can revise pricing or optimize workflow to improve margins. Regular P&L review also helps service businesses plan for expansion, hire new staff, or invest in technology without compromising profitability.
Another benefit of a profit and loss statement for service business is transparency. Stakeholders, including partners and investors, can quickly understand the company’s financial health. This transparency builds trust and aids in decision-making, ensuring that any growth strategies are backed by solid financial data.
Self Employment Profit and Loss Statement
Freelancers and independent contractors benefit immensely from a self employment profit and loss statement. Unlike larger organizations, self-employed individuals often manage income and expenses themselves, making accurate financial tracking crucial. This statement provides a clear overview of all earnings and costs associated with running a business as an individual.
For example, a freelance web developer’s P&L might list project income, software subscriptions, internet fees, marketing campaigns, and equipment purchases. By organizing all data in a self employment profit and loss statement, they can see exactly how much they earn after deducting expenses, making tax preparation straightforward and reducing the risk of errors or missed deductions.
Moreover, maintaining a self employment profit and loss statement allows individuals to forecast future income and expenses. This is especially valuable in industries where income is inconsistent or project-based. By analyzing trends over several months, freelancers can better plan budgets, save for taxes, and set aside funds for slow periods.
Benefits of Regular P&L Review
Whether you are running a small business, a service company, or operating as a self-employed individual, reviewing your P&L regularly is essential. Benefits include:
- Improved decision-making: Understand which areas generate profits and which require cost reductions.
- Accurate tax reporting: Organize revenue and deductible expenses to ensure compliance.
- Cash flow management: Monitor inflows and outflows to avoid financial shortfalls.
- Business strategy optimization: Identify trends and plan growth or service adjustments.
- Stakeholder confidence: Presenting a clear financial picture increases credibility with investors, partners, or lenders.
Conclusion: Taking Control of Your Finances
A well-prepared profit and loss statement for small business, along with its variants for self-employed individuals, personal finances, and service-based companies, is more than a simple accounting document. It is a strategic tool that enables informed decisions, effective growth planning, and sustainable financial health. By investing time in accurate P&L preparation and analysis, business owners and freelancers alike can confidently manage their operations and secure long-term success.